Quick Answer
Yes. A CLUE report error can cost you auto insurance offers, renewals, and premium amounts. If incorrect accidents, claims, or driver information make you appear riskier, you may face higher rates or an adverse coverage decision.
What Is a CLUE Report?
A Comprehensive Loss Underwriting Exchange (CLUE) report is a specialty consumer report containing insurance claims data.
How CLUE Reports Work
LexisNexis maintains CLUE auto reports using information from participating insurers. Reports may include up to seven years of auto claims history.
What Information Appears in a CLUE Report
Reports may include drivers, vehicles, policies, claims, losses, and related details.
How Insurers Use CLUE Reports When Evaluating Coverage
Insurers may use CLUE information to assess insurance history and risk.
New Policy Applications
A carrier may review prior claims when deciding whether to issue coverage and on what terms.
Policy Renewals
Claims history may also affect renewal, subject to applicable law.
Underwriting Decisions
CLUE information can affect eligibility and premiums.
Can a CLUE Report Error Lead to an Auto Insurance Coverage Denial?
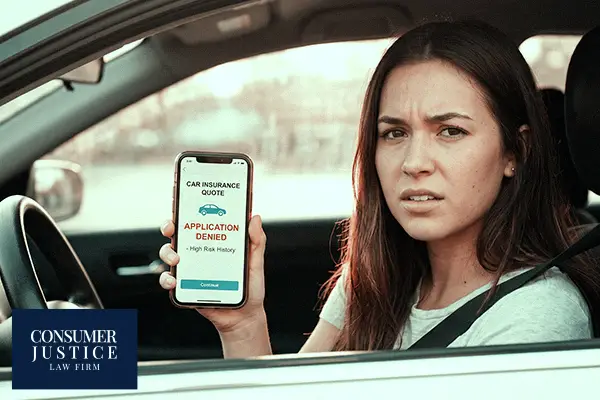
Yes. A CLUE report error may lead to an auto insurance coverage denial by inaccurately reflecting an applicant’s claims history.
Incorrect Accident Records
An accident may be attributed to the wrong driver or vehicle.
Claims That Do Not Belong to You
Another person’s insurance claim may mistakenly appear in your file.
Duplicate Claims Entries
A single incident may incorrectly appear more than once.
Identity Theft and Mixed File Errors
Identity theft or information belonging to another consumer may cause incorrect records.
Common CLUE Report Errors That Can Affect Coverage
Inaccurate Claims Histories
Reports may contain claims that are incorrect, incomplete, or improperly attributed.
Incorrect Driver or Vehicle Information
Errors involving names, vehicles, addresses, or identifying information can affect how records are matched.
Outdated Claims Information
Information that should no longer be reported may remain in a file.
Claims Listed With Incorrect Fault Determinations
Incorrect claim details may create a misleading picture of an applicant’s insurance history.
Warning Signs Your CLUE Report May Contain Errors
Unexpected Coverage Denials
A denial that appears inconsistent with your known insurance history may warrant reviewing your report.
Non-Renewal Notices
Incorrect claims information may contribute to a non-renewal decision.
Increased Underwriting Scrutiny
Requests for explanations about accidents or claims you do not recognize may indicate an error.
Higher-Than-Expected Premium Quotes
Unexpectedly high premiums may also justify checking the information insurers are using.
Your Rights When a CLUE Report Contains Inaccurate Information
CLUE reports are consumer reports subject to the Fair Credit Reporting Act (FCRA).
Accessing Your CLUE Report
Consumers can request their LexisNexis consumer disclosure and review the information being reported.
Disputing Errors
The FCRA allows consumers to dispute information they believe is inaccurate or incomplete.
Requesting Corrections
The consumer reporting company must conduct a reasonable investigation and correct or remove information when required.
How to Dispute a CLUE Report Error
Understanding how to dispute a CLUE report is the key to preventing or fixing costly errors.
Review the Report for Inaccuracies
Identify each claim, accident, vehicle, or personal detail you believe is incorrect.
Gather Supporting Documentation
Collect insurance records, police reports, claim correspondence, identification, or other supporting evidence.
Submit a Formal Dispute
Dispute the information with LexisNexis and identify what is inaccurate.
Follow Up on the Investigation
Review the results and confirm whether the information was corrected or removed.
What Happens if an Error Is Not Corrected?
If a CLUE report error is not corrected, it may continue affecting insurance and lead to further dispute or legal options.
Continued Coverage Problems
An unresolved error may affect future applications, renewals, or premiums.
Potential Legal Claims
Failure to properly investigate or correct inaccuracies may create FCRA rights.
Escalating the Dispute
Consumers may provide more documentation, dispute with the furnisher, file regulatory complaints, or seek legal advice.
Can You Sue Over a CLUE Report Error?
You may be able to sue if the circumstances support an FCRA claim.
Potential Fair Credit Reporting Act (FCRA) Claims
Claims may arise when an agency or furnisher violates FCRA obligations.
Failure to Conduct a Reasonable Investigation
A claim may arise when disputed inaccurate information is not reasonably investigated.
Damages Available to Consumers
The FCRA may allow actual damages, statutory or punitive damages, attorney’s fees, and costs.
How a Consumer Protection Attorney Can Help
A consumer protection attorney can evaluate whether inaccurate reporting caused legally actionable harm.
Frequently Asked Questions
What is a CLUE report?
A CLUE report contains auto insurance claims history.
Can a CLUE report error cause an auto insurance company to deny coverage?
Yes. Incorrect claims can affect underwriting.
What types of mistakes commonly appear on CLUE reports?
Incorrect claims, duplicates, wrong driver information, or another person’s claims.
How can I find out whether my CLUE report contains errors?
Request your LexisNexis consumer disclosure and review it.
What should I do if a claim appears on my CLUE report that does not belong to me?
Dispute the claim and provide documentation showing why it is inaccurate.
Can identity theft affect my CLUE report?
Yes. Fraud or mixed files can create erroneous records.
How do I dispute inaccurate information on a CLUE report?
Dispute the information with LexisNexis and provide evidence.
How long does it take to correct a CLUE report error?
FCRA investigations generally take 30 days, or up to 45 in some cases.
What are my rights under the Fair Credit Reporting Act (FCRA)?
You may access your report, dispute errors, and receive an investigation.
Can an insurance company cancel or refuse to renew my policy because of incorrect CLUE report information?
Yes. Incorrect CLUE information may contribute to cancellation or non-renewal.
Can I sue if a CLUE report error caused me to lose coverage?
Potentially, if the circumstances support a legal claim.
What compensation may be available in a CLUE report error lawsuit?
Remedies may include damages, attorney’s fees, and costs.
When should I contact a lawyer about a CLUE report error?
Consider legal advice if an unresolved error causes financial harm.