You Need Credit.
Americans submit loan and credit card applications by the tens of millions every year. Credit report errors unfairly block approvals, and often people don’t even realize errors played a role.
Credit report errors block loans, housing, cars, insurance, and jobs — and most people never learn that a mistake was the reason.
Get a Free Case Review Now
(844) 808-2553No Justice, No Fee ™
Americans submit loan and credit card applications by the tens of millions every year. Credit report errors unfairly block approvals, and often people don’t even realize errors played a role.
Whether it’s a mortgage application or a rental application, an inaccurate credit report can stop your application in its tracks or lead to higher deposits and worse rates.
Driving your kids, getting to work, visiting family — many of us depend on cars in daily life, but can’t afford one without financing. Misleading credit data can prevent you from getting a car loan or make you pay more than you should.
Without insurance, your family’s future, home, personal belongings, car, health, and more, are uncertain. A mistake in your credit report can cause coverage denials or higher rates.
If your career requires a credit check, having wrong information in your credit report can be an employment deal breaker.
We are a nationwide credit reporting law firm that helps consumers throughout the U.S., including Arizona, California, D.C., Florida, Georgia, Illinois, Maryland, Michigan, Minnesota, Nevada, New Jersey, New York, Pennsylvania, Texas, Washington, and everywhere else you are. Coast-to-coast legal help you can count on.
Credit report errors include any information that is inaccurate, incomplete, misleading, duplicate, false, someone else’s, outdated, or unreportable.

You have the right to accurate credit reports, free from errors.
You have the right to dispute errors and demand corrections. The credit bureaus have an obligation to investigate and fix their mistakes.
If Experian, Equifax, or TransUnion ignore or mishandle your dispute, file a lawsuit.
If you suffer financial, housing, career, reputational, emotional, or other harm, you may be able to get compensation.
The answer is often both. Sometimes, a dispute can help clear errors, but if the credit bureaus — Equifax, Experian, and TransUnion — ignore or mishandle your dispute, a lawsuit is the next step. Other times, the harm caused by credit report errors is so bad, a lawsuit is the best place to start. We help determine the right legal strategy for your situation.
Due to mixed files, identity theft, or bad data.
Late or missing payments reported in error.
Reported as delinquent, charged off, or in collections when it isn’t.
Throwing off your credit utilization score.
On accounts, payment data, debts, or anything else.
Someone else’s info mixed into yours.
That should have been removed by now.
Wrong name, address, SSN, employer.
That lower your credit score and raise red flags.
Bankruptcies, judgments, and liens that are wrong.
Mistakenly marked as deceased.
Info that’s not yours, not accurate, or no longer reportable.
When Experian’s automated matching system falsely linked our client’s credit and financial information with his adult son’s information, the mistake was disastrous. Having a credit report filled with mistakes and wrong information caused multiple lending denials that cut off his access to much-needed credit.
Our attorneys worked tirelessly to prove the facts of this case within the context of a powerful legal strategy.
“This trial showed the real-world consequences of inaccurate credit reporting.”
Civil Action No. 4:24-cv-00637 (E.D. Tex. 2026)
$95,000
Here’s what we did:
Your trial team
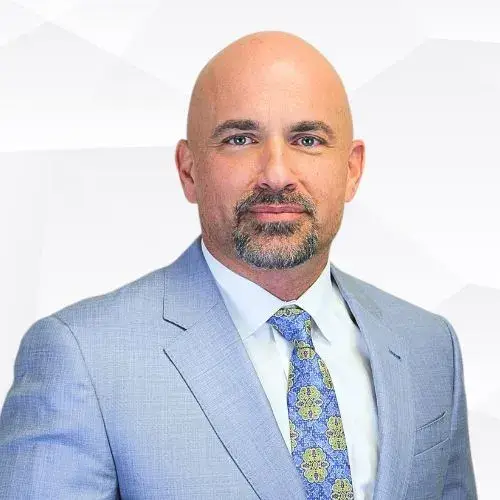
David Chami
Managing Partner
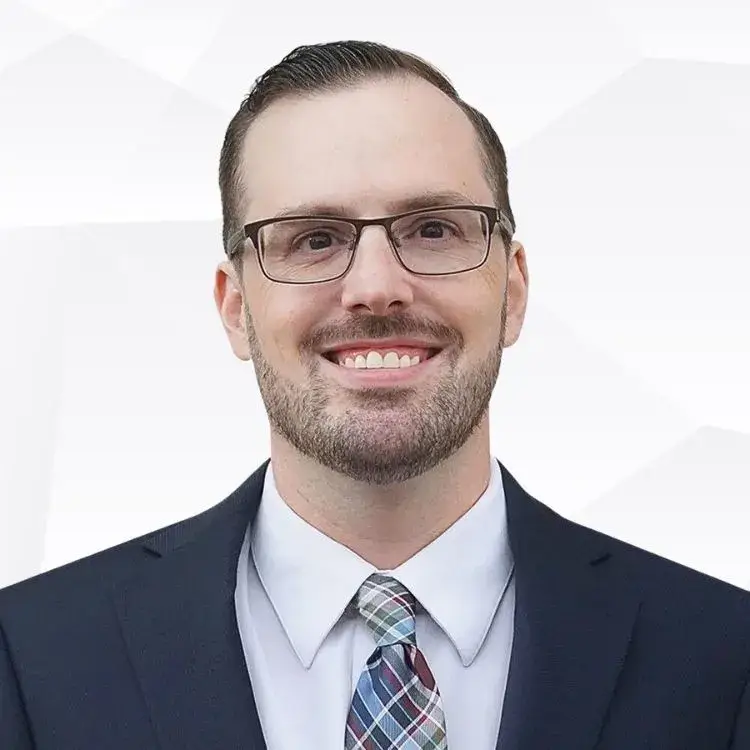
James Ristvedt
Managing Attorney & Trial Counsel
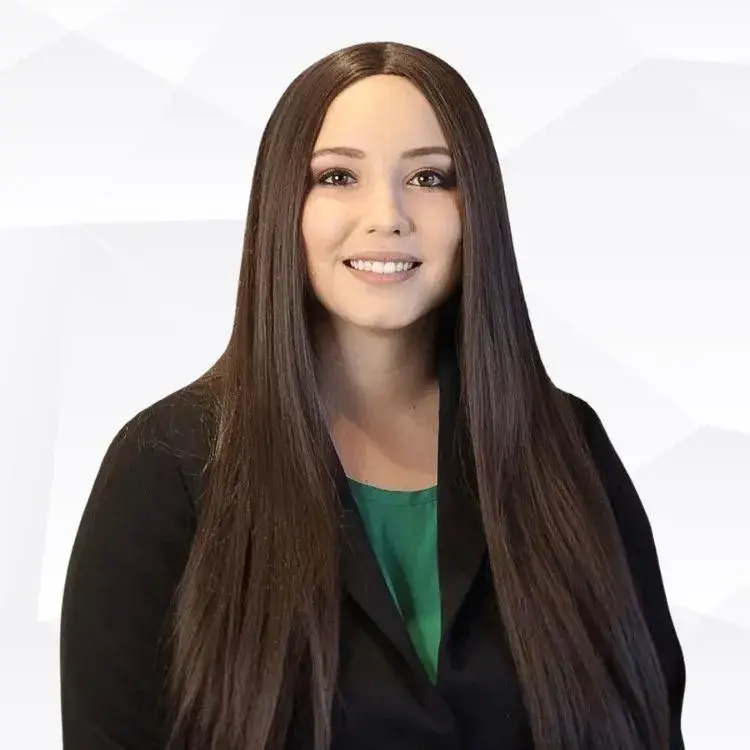
McKenzie Czabaj
Associate
We chose you. Our attorneys chose to work for one of the largest credit reporting practices in the nation. We use our legal resources and experience to help consumers fight corporations over inaccurate credit reporting…every single day.
To dispute a credit report error, start by carefully reviewing all three credit reports, clearly mark any errors that you find, find supporting documents, submit a written dispute by certified mail (include a dispute letter and copies of evidence), keep all emails, communications, and mail receipts, and track the time from the day they receive it (30 days).
Under the FCRA, the credit bureaus typically have 30 days from when a dispute is received to investigate and respond, including removing incorrect or unverifiable data. Under some limited circumstances, it can take up to 45 days. Failing to properly investigate and respond to disputes or correct errors is a violation of your FCRA rights.
Yes. You have a right to seek compensation for credit reporting errors under the Fair Credit Reporting Act (FCRA). You may be entitled to compensation for harms like financial and other losses related to loan, job, housing, and insurance denials, including reputational and emotional damage.
If you work with Consumer Justice Law Firm, it does not cost you anything to speak with an attorney. We offer free case reviews to determine whether you have a viable claim, and if we take your case, you do not pay any money up front or out of pocket. The credit bureaus and other companies pay our legal bills when we win.
Yes. Identity theft can result in unauthorized accounts, debts, loans, mortgages, rentals, insurance claims, and more, wrong personal information, and fraudulent transactions that show up on your credit report and linger long after the identity theft itself has been caught. There are steps you can take to start cleaning up the data mess. Talk to a lawyer to build a personalized legal recovery plan including help filing disputes and lawsuits if needed.
We help you handle
No Justice, No Fee ™